Welcome to Ecobanka World

Mortgage EXPRESS:

Private Direct Investment

Choosing a Mortgage Type

Mortgage EXPRESS:

Private Direct Investment

Choosing a Mortgage Type

Mortgage EXPRESS:

Property for Sale + RENOVATION

Renovate to Enjoy or Resell

Mortgage EXPRESS:

Property Ownership + Renovation

Your ideal design to increase your property's value
Mortgage EXPRESS:

Property Ownership + Renovation

Your ideal design to increase your property's value
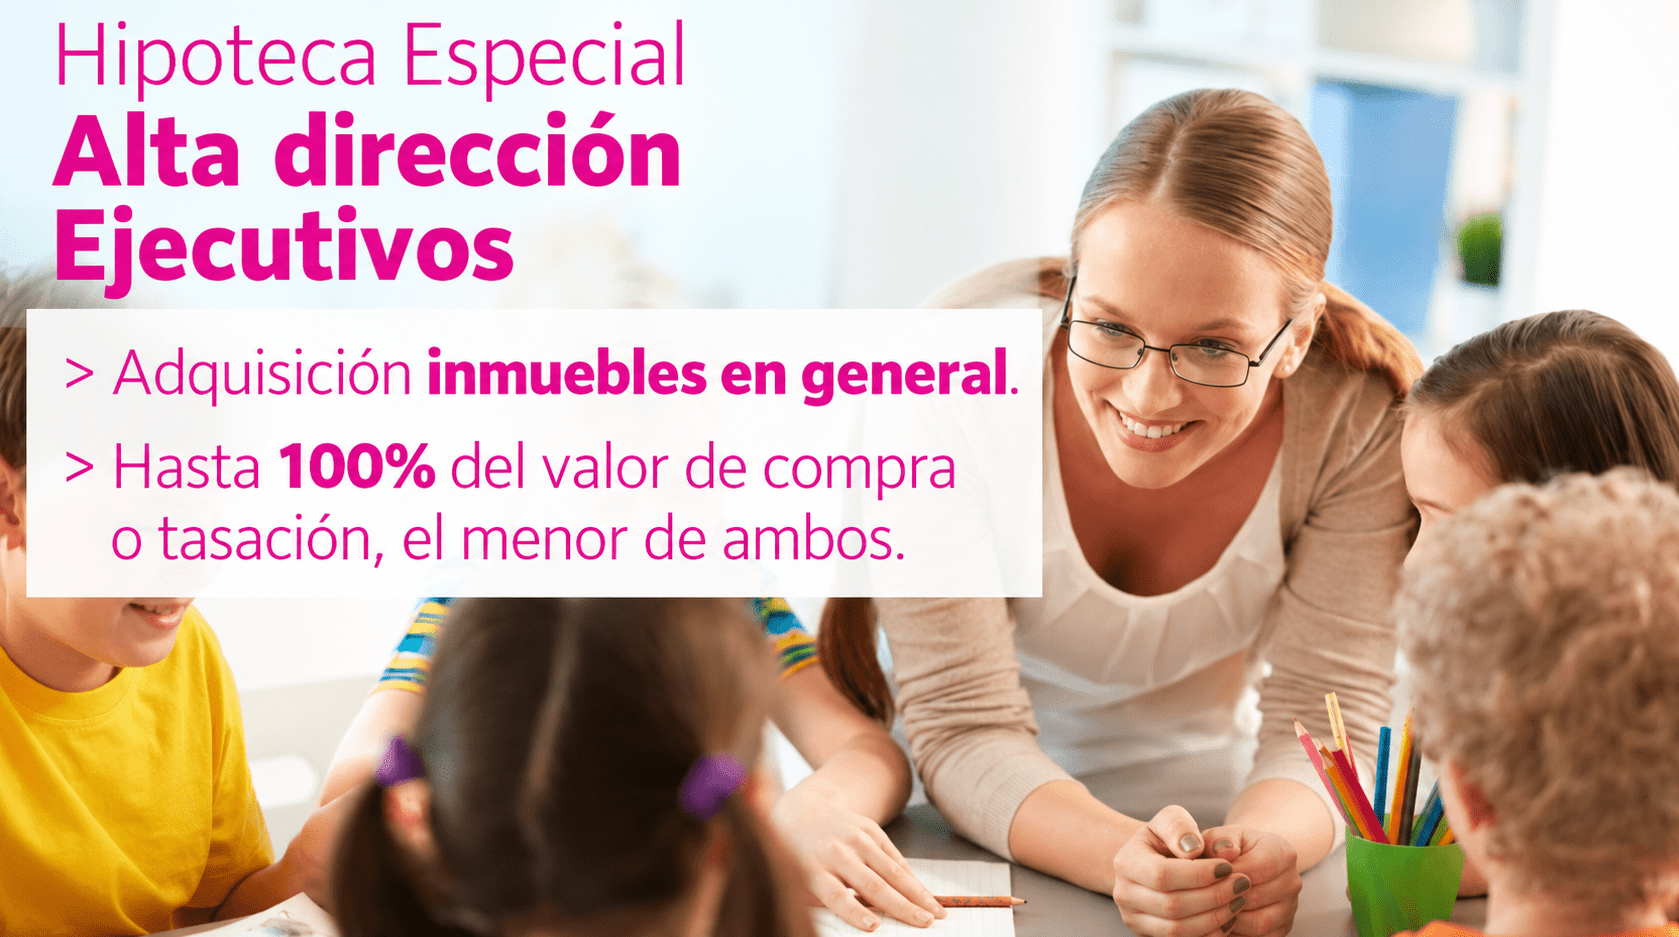
Mortgage EXPRESS: 

Entrepreneurs

Residents and Digital Nomads

Non-residents

Express Mortgage:

Senior Management Executives

The choice is yours:

Fixed, Variable, Mixed or Green

Pay over 15, 20, 30, and 40 years

EXPRESS mortgages:

Senior Management Executives

The choice is yours:

Fixed, Variable, Mixed or Green

Pay over 15, 20, 30, and 40 years

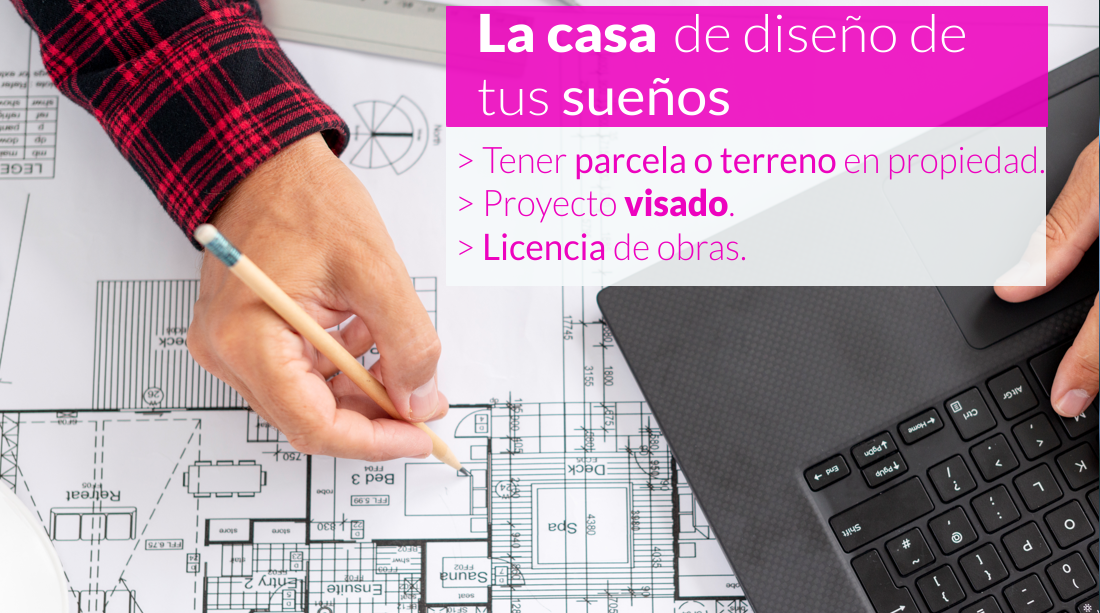
Mortgage EXPRESS:

Autopromotor

Build your own house and save up to 30% of your budget.

Advance payment and milestone deliveries until completion.
Express Mortgage:

Executives and Professionals

Tailor-made mortgage

Express Mortgage:

Executives and Professionals

Tailor-made mortgage

Mortgage EXPRESS:

Second Residence

Financing up to 70% of the value.

Repayment term up to 25 or 30 years.
Mortgage EXPRESS:

Multi-jurisdiction · Nonresidents

Financing up to 70% of the value.

Term up to 25 years.

Mortgage EXPRESS:

Multi-jurisdiction · Nonresidents

Financing up to 70% of the value.

Term up to 25 years.

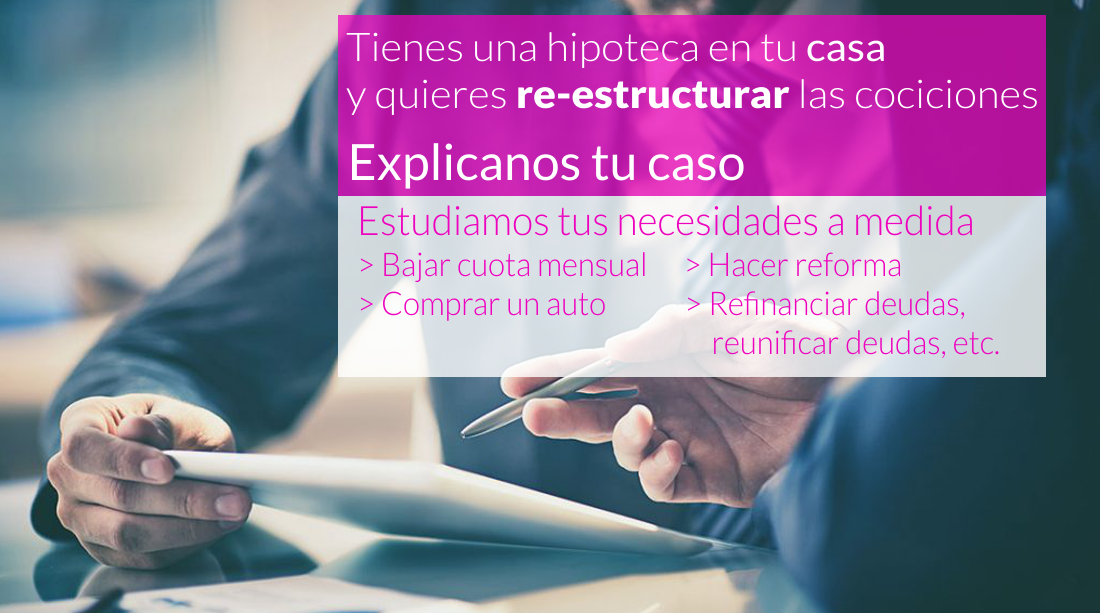
Mortgage EXPRESS:

New Restructuring 

Planning and Re-Estructuring, Improving conditions in:

Interest rate.

Fee payable.

Amortisation period.
Mortgage EXPRESS:

Green Eco-Construction

Acquisition, construction or rehabilitation.

Bonuses in general conditions for sustainability.

Mortgage EXPRESS:

Green Eco-Construction

Acquisition, construction or rehabilitation.

Bonuses in general conditions for sustainability.

Mortgage EXPRESS:

Properties for Rent

Obtain monthly tenant rents.

Obtain rents from tourist platforms.

Another direct retailer.
Frequently Asked Questions

Our corporate manager can help you:

Prerequisite: An executive with an established investment company or sole proprietorship is a prerequisite. We do not conduct business with individuals; a business entity is required. 
-
Proposed Terms. We conduct a digital analysis and present a preliminary quote for your approval.

What are mortgages?

A mortgage is a banking product that is used to obtain financing for the purchase of real estate. The person interested in the mortgage receives an amount of money called the loan capital from a lender, which can be a bank or any other credit institution.

All mortgages are subject to a commitment on the part of the customer to repay the amount borrowed as well as the interest generated. This repayment is made effective through the payment of mortgage instalments. One of the most characteristic differences of mortgages compared to other types of loans is the additional guarantee, which will be the property acquired.

What are mortgage loans made up of?

In any mortgage that you can get there are two components that you must take into account. Firstly, you will find the mortgage loan contract, here you will be able to see all the conditions of the mortgage and the obligations you must fulfil in order to receive the capital as a debtor. You will also be able to check the following points of the mortgage:

  • The repayment period.
  • Mortgage repayments.
  • The complete mortgage repayment system.

The second component is the mortgage guarantee. This is a very important part of any mortgage because, if the mortgage loan is defaulted on, the lender has the right to keep the property that has been mortgaged. Before taking out a mortgage you should bear in mind that it is a large, long-term financial commitment. For this reason, you must have a correct, regular and timely income according to the debt you are going to accept and consider the initial savings before getting into debt.

What are the keys to know how much mortgage you need?

Not only the amount but also the repayment term and the instalment, but these are two of the factors that will decide the total mortgage:

  • The valuation of the property. Only authorised appraisers can carry out the appraisal of your home and then be accredited by the Bank of Spain. Some banks and other entities offer from 60% to 80% of the financing, although some banks are currently offering 100% mortgages in some specific cases and as long as the financial profile and economic conditions of the client allow it.
  • The client's indebtedness. The lending institutions carry out a study of the client where, through the income and expenses, they can determine the amount of money that you can allocate to the mortgage instalment. In addition, it is important to have between your savings an amount close to 20-25% of the value of the property and another 10% for the expenses of the operation.

What types of interest are there?

Depending on the interest rate established in the mortgage contract, there are different types of mortgages, among which are the following:

  • Fixed mortgages. In this case, the interest established in the mortgage contract is fixed, so the monthly mortgage payment will be fixed for the entire term of the mortgage loan, i.e. it will remain constant even if market interest rates rise and fall.
  • Variable mortgages. The interest on these mortgages is variable and is made up of the value of the reference index and a fixed differential. The amount of the mortgage instalments is revised annually or half-yearly and the instalments to be paid are updated.
  • Mixed mortgages. This type of mortgage is a hybrid of the two previous ones, since during one term they are at a fixed rate and during the rest of the term they have a variable interest rate.

What are the costs associated with the mortgage?

The costs associated with taking out a mortgage are usually 3% of the amount of the loan. The costs associated with mortgage loans include:

  • Land Registry.
  • Notary fees.
  • Costs of the valuation of the property.
  • Tax on the formalisation of the mortgage loan.
  • Mortgage processing fees.

What are the fees for mortgages?

When calculating the cost of the mortgage we have to take into account a series of factors, among which are the commissions. For example, the origination fee is presented as soon as the mortgage loan application is formalised and represents a percentage of the amount of the mortgage. But there are also some other commissions such as:

  • Study and ManagementCommission.
  • Earlyredemption fee.
  • Commission for formalisationcosts.

Our corporate advisor can help you:

Prerequisite: An executive with an established investment company or sole proprietorship is a prerequisite. We do not conduct business with individuals; a business entity is required. 
-
Proposed Terms. We conduct a digital analysis and present a preliminary quote for your approval.

What are mortgages?

A mortgage is a banking product that is used to obtain financing for the purchase of real estate. The person interested in the mortgage receives an amount of money called the loan capital from a lender, which can be a bank or any other credit institution.

All mortgages are subject to a commitment on the part of the customer to repay the amount borrowed as well as the interest generated. This repayment is made effective through the payment of mortgage instalments. One of the most characteristic differences of mortgages compared to other types of loans is the additional guarantee, which will be the property acquired.

What are mortgage loans made up of?

In any mortgage that you can get there are two components that you must take into account. Firstly, you will find the mortgage loan contract, here you will be able to see all the conditions of the mortgage and the obligations you must fulfil in order to receive the capital as a debtor. You will also be able to check the following points of the mortgage:

  • The repayment period.
  • Mortgage repayments.
  • The complete mortgage repayment system.

The second component is the mortgage guarantee. This is a very important part of any mortgage because, if the mortgage loan is defaulted on, the lender has the right to keep the property that has been mortgaged. Before taking out a mortgage you should bear in mind that it is a large, long-term financial commitment. For this reason, you must have a correct, regular and timely income according to the debt you are going to accept and consider the initial savings before getting into debt.

What are the keys to know how much mortgage you need?

Not only the amount but also the repayment term and the instalment, but these are two of the factors that will decide the total mortgage:

  • The valuation of the property. Only authorised appraisers can carry out the appraisal of your home and then be accredited by the Bank of Spain. Some banks and other entities offer from 60% to 80% of the financing, although some banks are currently offering 100% mortgages in some specific cases and as long as the financial profile and economic conditions of the client allow it.
  • The client's indebtedness. The lending institutions carry out a study of the client where, through the income and expenses, they can determine the amount of money that you can allocate to the mortgage instalment. In addition, it is important to have between your savings an amount close to 20-25% of the value of the property and another 10% for the expenses of the operation.

What types of interest are there?

Depending on the interest rate established in the mortgage contract, there are different types of mortgages, among which are the following:

  • Fixed mortgages. In this case, the interest established in the mortgage contract is fixed, so the monthly mortgage payment will be fixed for the entire term of the mortgage loan, i.e. it will remain constant even if market interest rates rise and fall.
  • Variable mortgages. The interest on these mortgages is variable and is made up of the value of the reference index and a fixed differential. The amount of the mortgage instalments is revised annually or half-yearly and the instalments to be paid are updated.
  • Mixed mortgages. This type of mortgage is a hybrid of the two previous ones, since during one term they are at a fixed rate and during the rest of the term they have a variable interest rate.

What are the costs associated with the mortgage?

The costs associated with taking out a mortgage are usually 3% of the amount of the loan. The costs associated with mortgage loans include:

  • Land Registry.
  • Notary fees.
  • Costs of the valuation of the property.
  • Tax on the formalisation of the mortgage loan.
  • Mortgage processing fees.

What are the fees for mortgages?

When calculating the cost of the mortgage we have to take into account a series of factors, among which are the commissions. For example, the origination fee is presented as soon as the mortgage loan application is formalised and represents a percentage of the amount of the mortgage. But there are also some other commissions such as:

  • Study and ManagementCommission.
  • Earlyredemption fee.
  • Commission for formalisationcosts.

Become an Ecobanka Client

Important News

Ecobanka News

Joining in and attendance at events

Press appearances

Subscribe to the Newsletter


    Important News

    Ecobanka News

    Joining in and attendance at events

    Press appearances

    Subscribe to the Newsletter